

Payactiv

- 9.10K Reviews
- 4.4
- Downloads
- 1,000,000+
Our take on Payactiv from Appgk
If you are paid by the hour and sometimes need money before payday, Payactiv is the kind of finance app I would consider before turning to a credit card or overdraft. Its purpose is straightforward: help eligible workers access wages they have already earned and work toward better day-to-day financial control. I found the idea more useful when treated as a cash-flow tool rather than as extra income. It does not make a tight budget disappear, but it can make the gap between an earned shift and the regular paycheck less stressful.
The app is free, aimed at everyone, and developed by On-demand pay and beyond. It has been available since June 4, 2014, and its current version is 2.2.8 for devices running at least OS 10. Its audience is already substantial, with over a million installs, an average rating of 4.4, and roughly forty-five thousand ratings. Those figures suggest that many people find the basic idea practical, although they should not replace checking whether your own employer and pay arrangement are supported.
What to expect before you begin
The first thing I would clarify is what “early pay” means here. The useful balance is connected to wages you have earned, not a new loan that increases your income. That distinction matters. If you use the app to handle a timing problem, such as a utility bill arriving before payday, it may be a sensible bridge. If you use it repeatedly to spend more than your normal paycheck can support, it can simply move the same shortage earlier in the month.
Payactiv makes the most sense for people whose employer participates in its earned-wage arrangement. That is the first practical checkpoint, and it is more important than the app’s attractive promise of faster access. I would install it with my employer information and payroll details ready, rather than expecting to open it and immediately withdraw money. Eligibility, available wages, and the actions offered to you can depend on how your workplace reports hours and pay.
Best Parts of Payactiv
Things to Keep in Mind About Payactiv
Once inside, I would expect the app to be useful in two connected ways. The immediate side is seeing whether part of earned pay is available before the normal payday. The longer-term side is using the service as a prompt to think about bills, spending timing, and financial goals. The second part is easy to overlook because urgent cash is more emotionally noticeable, but it is where the app can become more than a one-off emergency button.
There is also an important trade-off compared with a conventional bank app. A bank app usually shows money that has already reached your account and helps you move or organize it. Payactiv is focused on the period before that regular deposit arrives. Compared with a credit card, it is tied to earned wages rather than a revolving credit balance. That can be healthier for a short timing issue, but it also means the app cannot help if there are no eligible wages available.
News and Features Related to Payactiv

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Who will get the most from it
I would point first-time users toward Payactiv if they receive regular wages, occasionally face bills before payday, and want to avoid borrowing against future income. It may also suit someone who wants a clearer view of how much of a paycheck has already been earned during a pay period. The app is especially relevant when a small interruption, such as a transport cost or an unexpected household expense, would otherwise force a more expensive financial choice.
I would be more cautious if your income is irregular, your employer does not participate, or you already struggle because every paycheck is spent immediately. In those situations, early access can solve today’s problem while making the next payday feel smaller. Someone looking for detailed investing tools, full bank-account management, or a broad budgeting platform may also prefer a dedicated app built specifically for those tasks.
Don't want to read the full review?
Setting up the account without guessing
My advice is to approach setup as an eligibility check, not as a promise of instant cash. Install the app, identify your workplace accurately, and follow the verification steps it presents. Keep your personal and employment information consistent with your payroll records. Small mismatches are the sort of friction that can make a financial app feel broken even when the underlying service is working normally.
I would also read each screen before confirming a transfer or selecting an access method. Financial apps often present several choices with different timing or conditions, and the fastest-looking option is not automatically the best one for every situation. Payactiv is free to install, but “free app” should not be interpreted as “every possible transaction is free.” Before moving money, I would look carefully at any displayed cost, timing, or requirement connected to that particular action.
Screenshots
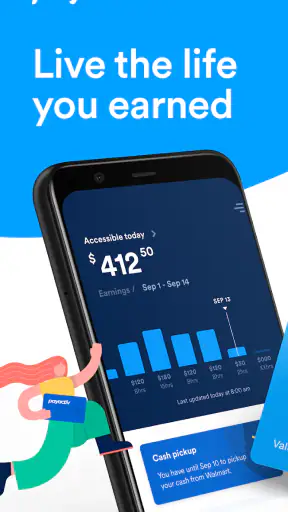
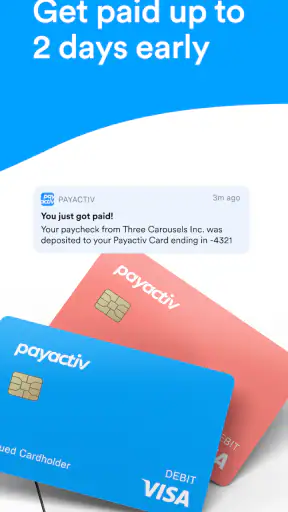
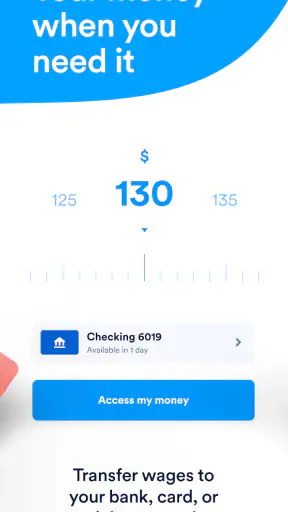
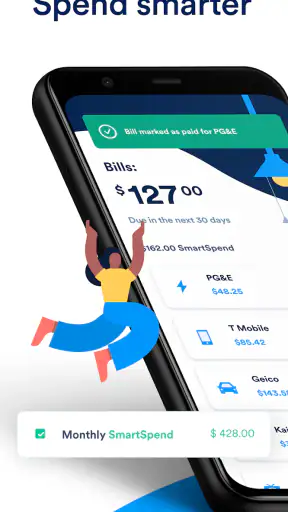
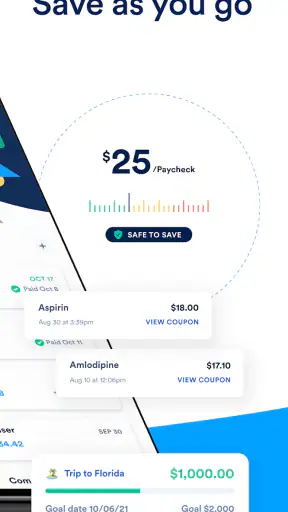
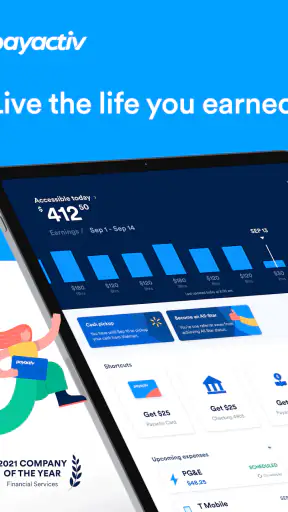
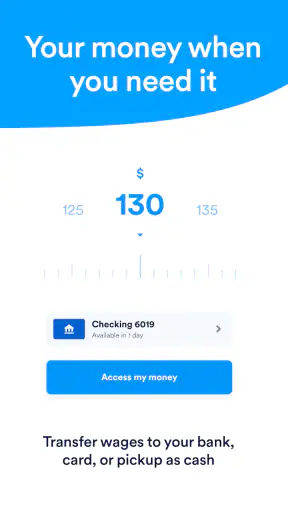
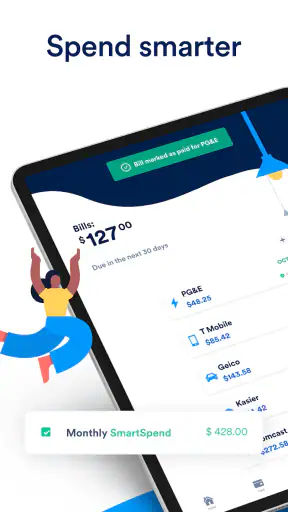
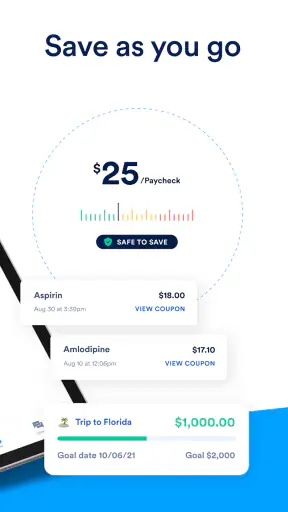
A useful setup habit is to decide in advance what the app is for. For example, I might use it only for a genuine shortfall involving food, transportation, or a bill that cannot wait. I would not treat the available amount as a spending target. That personal rule is valuable because an app showing accessible wages can make earned money feel more available than it really is in the context of the whole pay period.
Another practical step is to compare the app’s information with your own pay records. If the available amount does not match your expectations, first check whether all recent hours have been reported and whether the current pay period is the one you intended to view. Payroll timing can create a delay between working a shift and seeing it reflected. I would avoid repeatedly requesting help or making duplicate actions until I had checked those basics.
Privacy and account confidence
Because this is a finance app connected to employment and wages, I would use a strong device passcode and avoid signing in on a shared phone. I would also review notifications so sensitive financial details are not displayed where other people can see them. These are simple habits, but they matter more here than they would in a casual shopping or entertainment app.
I would keep the app updated when a new version is offered, particularly because the installed version is 2.2.8 and mobile finance services can change their screens and workflows over time. At the same time, I would not assume an update will resolve an employer-side reporting delay. The app can display and process information, but it cannot make unreported hours appear instantly.
Reaching the first meaningful result
For a new user, the first successful action should not be “take out as much as possible.” It should be confirming that the app recognizes your employment situation and clearly shows what, if anything, is available. That confirmation gives you a useful answer even if you decide not to move money. You learn whether the service fits your pay cycle before relying on it during a real emergency.
If an amount is available and you genuinely need it, I would choose one small, specific purpose. Suppose I have worked several shifts, my phone bill is due before payday, and waiting would trigger a late problem. I can check the available earned amount, review the transfer details shown in the app, and use only what covers that bill. The success is not merely receiving money; it is resolving the immediate expense without turning the entire remaining pay period into a guessing exercise.
Afterward, I would write down the amount and remember that it will affect the normal paycheck. This is the most important mental adjustment for first-time use. Early access is not a bonus added to the next deposit. It is a change in when part of earned pay reaches you. If I forget that, the following payday can feel unexpectedly low even though the total wages have not changed.
A second useful workflow is to use the app before an emergency rather than during one. When I know a recurring bill is usually due several days before payday, I can check my expected cash flow early in the pay period. That gives me time to decide whether to wait, use available earned wages, or contact the bill provider. The app is more helpful when it supports a decision than when it becomes the final action taken in a panic.
I also like the idea of separating “available” from “wise to use.” The displayed amount may tell me what I can access, while my budget tells me what I should access. That distinction is a concrete way to use the financial-wellness side of the service. It turns a tempting balance into information rather than an automatic instruction to withdraw.
Making early pay work with a normal budget
If I used Payactiv regularly, I would build a simple payday routine. First, I would note any amount already accessed. Next, I would list the bills that must be covered from the upcoming paycheck. Finally, I would leave room for ordinary spending rather than allocating every dollar in advance. This takes only a few minutes and helps prevent the common mistake of solving one urgent payment while creating a second shortage later.
For someone paid weekly, the effect may be easier to see because the pay cycle is shorter. For someone paid less often, early access may feel more valuable but also carries a greater risk of becoming habitual. In either case, I would judge the app by whether it reduces expensive financial stress over time, not by how quickly I can make a transfer on a single day.
Where new users commonly get confused
The biggest confusion is usually the difference between earned wages and a general cash advance. If the app does not show the amount you expected, that does not automatically mean your account is malfunctioning. The amount may depend on reported work and the employer’s connection with the service. I would first compare the app with recent hours and payroll information, then use the in-app support route if the mismatch remains.
Another confusing point is timing. “Early” does not necessarily mean identical instant access in every circumstance. A transfer can involve processing, account details, or a method selected inside the app. Before relying on it for a deadline, I would check the timing displayed for the exact action I am taking. If the bill is due within minutes, I would not assume that an early-pay app is a substitute for keeping a small emergency buffer.
Users may also wonder why their available amount changes. Earned-wage access is naturally linked to the current pay period, reported hours, and any amount already taken. I would treat the figure as a live estimate or available balance for the current situation, not as a permanent credit limit. Checking it once, acting, and then checking again later can produce a different result without indicating that money has vanished.
The financial-wellness language can create a different kind of misunderstanding. It does not mean the app can automatically repair debt, raise wages, or replace a complete financial plan. I see it as a practical layer around pay timing. For deeper debt repayment, savings automation, or investment decisions, I would still use tools designed for those purposes and keep Payactiv focused on the wage-access problem it is meant to address.
There is also a human issue: some people may feel pressure to use early pay because it is visible and convenient. My rule would be to pause before every request and name the expense it covers. If I cannot name the expense, I probably should not make the withdrawal. That small pause is one of the strongest safeguards against turning a helpful option into a recurring dependency.
Choosing it over familiar alternatives
Compared with asking a friend or family member for money, Payactiv can feel more private and structured because the access is connected to wages rather than a personal favor. Compared with a credit card, it avoids the particular cycle of carrying a balance and paying it down later, but it does not provide extra income. Compared with an overdraft, it may address the timing issue earlier, before a payment attempts to leave an empty account. The right choice still depends on the terms and timing shown for the specific transaction.
A traditional savings buffer remains better when you have one. Savings give you flexibility without reducing the next paycheck. I would use Payactiv as a backup while building that buffer, not as a replacement for it. Even a small amount set aside on each regular payday can reduce the number of situations in which early access feels necessary.
A budgeting app may be better if your main problem is not paycheck timing but unclear spending. Budgeting tools can show categories, recurring costs, and longer-term patterns in greater depth. Payactiv is more focused: it helps connect earned wages with immediate access and financial goals. I would choose it for the first problem and add a budgeting tool for the second rather than expecting one app to do both jobs equally well.
The next step after the first success
After using the app once, I would review what actually happened. Did the money arrive in time for the intended bill? Did accessing it make the next payday harder? Was the amount enough to solve the issue without encouraging extra spending? Those answers tell me more than the app’s rating or a quick first impression. They also help me decide whether Payactiv belongs in my regular routine or should remain an occasional fallback.
If the first use went well, I would set a personal limit based on my budget rather than on the maximum amount the app makes available. I would also keep a note of upcoming bills and payday dates so I can plan before the pressure arrives. This turns the service into a controlled part of cash-flow planning. Without that boundary, convenience can quietly become a reason to access wages earlier every time they appear.
If setup fails or the available amount looks wrong, I would not repeatedly reinstall the app or enter different employment details. I would verify the employer information, check recent payroll records, and then seek support through the app. Financial verification is frustrating, but guessing can create more confusion and may delay the very access I need.
My overall view is positive but deliberately narrow. Payactiv is a useful finance app for an eligible worker who needs to manage the gap between earning money and receiving the ordinary paycheck. Its free access, established presence, and strong user response make it worth investigating, but the real test is whether it helps you avoid a more expensive choice without causing a new shortage. Use the available wage as a carefully planned bridge, not as permission to spend ahead of your budget.
I would recommend it to a friend who has regular employment, occasional timing problems, and enough discipline to track what has already been accessed. I would suggest a savings or budgeting solution first to someone whose difficulties are ongoing or whose employer is not supported. Used with that distinction in mind, Payactiv can provide a reassuring first step: install it, confirm eligibility, understand the balance, solve one clearly defined need, and then decide whether the service genuinely improves your financial routine.
Payactiv FAQ
What is Payactiv, and how does it work?
Payactiv is a financial wellness app that can give eligible employees access to part of their earned wages before the regular payday. After connecting through a participating employer, the app displays available earnings based on recorded work hours. Users may transfer funds to a bank account, debit card, or other supported option, depending on their plan and location. It is not a traditional payday loan, but access and fees can vary.
Who can use Payactiv?
Payactiv is generally available to employees whose employers participate in the Payactiv earned-wage-access program. Individual users normally cannot activate the full service without an eligible employer connection. During registration, the app may ask for identifying information and employment verification, and availability can depend on payroll integration, work schedules, location, and company policies. If your employer is not supported, some additional financial tools may still be visible, but wage access may not be available.
How quickly can I receive money through Payactiv?
Transfer speed depends on the delivery method selected, your employer’s payroll setup, banking details, and whether the request is processed during supported hours. Some transfers may arrive quickly, particularly when sent to an eligible instant-transfer account or card, while standard bank deposits can take longer. Before confirming a transaction, review the estimated arrival time and any applicable fee shown in the app, since timing is not identical for every user.
Does Payactiv charge fees for accessing earned wages?
Payactiv may offer certain ways to access earned wages at no cost, but fees can apply depending on the transfer method, membership or employer arrangement, card usage, or optional services. The exact pricing is not universal because employers and regions may have different agreements. Check the fee disclosure displayed before requesting money, and remember that using earned-wage access regularly can affect your normal paycheck amount on payday.
Is Payactiv safe to use, and what should I consider before downloading it?
Payactiv uses account verification and security measures intended to protect personal, employment, and financial information, but no financial app is completely risk-free. Download it only from an official app store, use a strong unique password, and enable available security features. Before enrolling, read the privacy policy, fee information, employer terms, and repayment or payroll conditions carefully. Also confirm that the app supports your employer and preferred transfer method.











